Start here: this article is part of our inherited property collection. For the full picture, read our complete guide, How to Sell a House in Probate: Step-by-Step Guide for Executors and Heirs.
Quick answer: When the owner dies, the mortgage stays on the house. Federal law generally stops the lender from calling the loan due when the home passes to a relative, so heirs can keep paying, refinance, or sell and pay it off at closing. SilverCrest Estates suggests four first steps: tell the servicer, show your authority, keep payments current and compare your options.
| Step | What to do |
|---|---|
| Tell the servicer | Send a copy of the death certificate |
| Show authority | Will, letters testamentary or executor letter |
| Keep paying | Avoid late fees while you decide |
| Decide | Keep, refinance, or sell and pay off |
What happens to a mortgage after death
The mortgage is a lien on the house, not a debt that vanishes with the borrower. It stays attached to the property until someone pays it off.
The loan balance, interest rate and monthly payment do not change because the borrower died. What changes is who handles it. During probate, the executor or administrator usually manages the house and decides whether to keep paying from estate funds. Once the house passes to an heir, that heir decides what happens next.
Heirs are not personally on the hook for the loan just because they inherit the house. If nobody pays, though, the lender can eventually foreclose on the property itself, which wipes out the equity the family could have kept or sold.
Does the mortgage have to be paid off right away?
No. The lender cannot simply demand the full balance because the owner died, as long as the house passed to a relative or a spouse.
The due-on-sale protection for family
Most mortgages have a due-on-sale clause. A federal law limits when lenders can use it.
The Garn-St Germain Act, at 12 U.S.C. 1701j-3(d), says a lender may not exercise a due-on-sale clause on a residential property with fewer than five dwelling units when the transfer is to a relative because the borrower died, when the spouse or children of the borrower become owners, or when a joint tenant's share passes at death. Transfers into some living trusts are covered too.
In plain terms, an adult child who inherits a parent's house can keep the existing loan and its interest rate. That matters when the old rate is lower than today's rates.
Becoming a successor in interest
The servicer will only talk to you about the account once it confirms who you are and that you own the house.
Federal servicing rules call this a "successor in interest." Under 12 CFR 1024.31, a confirmed successor in interest is someone whose identity and ownership the servicer has verified. After that, you can get statements and payoff figures and apply for help such as a loan modification.
Expect to send a copy of the death certificate plus proof of your right to the house. Depending on the state and the estate, that might be the will, letters testamentary from the probate court, an executor letter, or a recorded transfer-on-death deed. Ask the servicer exactly which papers it needs, in writing.
Who keeps paying while the estate is open?
Someone should keep the payments current. Late fees and missed payments shrink the equity the heirs will share.
If the estate has cash, the executor can usually pay the mortgage, taxes and insurance from estate funds. If not, an heir may pay to protect the house and ask to be reimbursed when it sells; keep receipts. Also call the homeowners insurer, since a vacant house may need a different policy. Our probate guide explains how the court process fits around these payments.
Suppose the house could list at $280,000 after $12,000 of updates, with $18,000 in selling costs and $6,000 in payments, taxes and insurance while it sits for four months.
Decision path: keep, refinance or sell
Each choice should end in a written number. Line them up before anyone signs.
Mortgage after death: first four steps
- 1
Tell servicer
Death certificate and contact details.
- 2
Show authority
Will, court letters or deed.
- 3
Keep paying
Protect equity while you decide.
- 4
Payoff or sale
Keep, refinance, or sell.
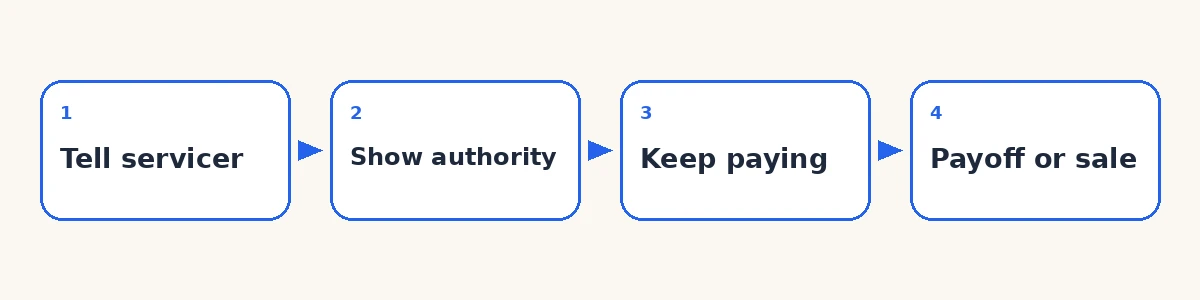
The loan does not disappear, so the first calls are about records and payments.
- Keep the house and the loan: works when the heir can afford the payment and wants to live in or rent the home.
- Refinance: useful when siblings need to be bought out, or the heir wants a loan in their own name.
- Sell and pay off: the mortgage payoff comes out of the sale proceeds at closing, and the rest goes to the estate or heirs.
- Several heirs disagree: get each option in writing so the decision rests on numbers, not guesses.
Worked example: what heirs actually receive
These figures are labeled examples, not typical results or SilverCrest offers. Use your own payoff statement and written offers.
Suppose the house could list at $280,000 after $12,000 of updates, with $18,000 in selling costs and $6,000 in payments, taxes and insurance while it sits for four months. With a $140,000 payoff, the example net to the estate is $104,000. An as-is offer of $262,000, with $2,500 in seller costs and one month of carrying costs at $1,500, leaves $118,000 after the same payoff.
In this example, the faster sale nets more because the updates and waiting cost more than the price difference. Your numbers may point the other way.
Reverse mortgages work differently
A reverse mortgage usually becomes due when the last borrower dies, so the timeline is tighter.
Heirs typically must repay the balance, sell, or sign the home over to the lender within set time frames. Read our reverse mortgage guide before you plan a sale.
When probate is not needed
Some houses pass outside probate through a trust, joint ownership or a transfer-on-death deed.
The mortgage still stays on the house in those cases; only the paperwork changes. See selling a house after death without probate and selling a house in a trust for how those transfers work.
When a cash sale may not be your best option
If an heir wants to keep the house, the payment is affordable and the old interest rate is low, keeping the loan may be the better plan.
If the home is move-in ready and the estate can carry the payments for a few months, listing with an agent may net more. Compare cash offers with listing and talk to a HUD-approved housing counselor if the payments are already behind.
Key takeaways
- The mortgage stays on the house after the owner dies.
- Federal law generally protects relatives from a due-on-sale demand.
- Become a confirmed successor in interest to get account details.
- Keep payments current while the estate decides.
- Compare written net figures for keeping, refinancing and selling.
Related seller guide
Surviving spouses can find title and tax steps in selling a house after a spouse dies.
The bottom line
A mortgage after death is a records problem first and a money decision second. Request a cash offer to see an as-is number next to your other options, or browse the inherited and probate hub. SilverCrest Estates can close in as little as 21 days when a quick sale fits the family's plan.
Frequently asked questions
What happens to a mortgage when the owner dies?
The loan does not go away. It stays secured by the house, and the estate or the heir who receives the home decides whether to keep paying it, refinance it, or sell the house and pay it off from the sale proceeds.
Can the lender call the loan due when the borrower dies?
Federal law, 12 U.S.C. 1701j-3(d), bars lenders from using a due-on-sale clause on a home with fewer than five units when it passes to a relative because the borrower died, or when a spouse or child becomes an owner.
Do heirs have to qualify for the mortgage to keep it?
Usually not. A relative who inherits the home can generally keep the existing loan without a new application. The servicer will ask for proof of ownership, such as the will, a death certificate or a letter from the executor.
Sources & further reading
Primary sources we consulted for this article. Rules vary by state and change over time — always confirm against the original source.
- 112 U.S. Code § 1701j-3 — Preemption of due-on-sale prohibitions
Legal Information Institute, Cornell Law School
Subsection (d) lists transfers at death that a lender may not treat as a due-on-sale trigger.
- 212 CFR § 1024.31 — Definitions (successor in interest)
Legal Information Institute, Cornell Law School
Defines a confirmed successor in interest, the status that lets an heir deal directly with the servicer.
- 3Find a Housing Counselor
U.S. Department of Housing and Urban Development
Free or low-cost HUD-approved counselors who help heirs with mortgage questions.
About the author
Jennifer Martinez
Real Estate Consultant
Jennifer Martinez works with the SilverCrest Estates acquisitions team, helping homeowners across 50+ US markets understand their options and close on their own timeline.
Disclaimer: This article is for general information only and is not legal, tax, or financial advice. Real estate rules vary by state and change over time. Consult a licensed attorney, tax professional, or financial advisor about your specific situation before acting.