Quick answer: Most Texas foreclosures move fast: once a servicer may start, a nonjudicial sale can follow in roughly two months. Federal rules usually require more than 120 days of missed payments first, then Texas requires at least a 20-day cure notice and 21 days' sale notice. SilverCrest Estates sees home equity loans take longer because they need a court order.
| Stage | Typical minimum |
|---|---|
| Missed payments before first notice | More than 120 days (federal rule) |
| Notice of default and opportunity to cure | At least 20 days |
| Notice of sale before the auction | At least 21 days |
| Sale day | First Tuesday of the month, 10 a.m. to 4 p.m. |
General education, not legal advice.
How long does foreclosure take in Texas?
From the first missed payment to the courthouse sale, a standard Texas foreclosure on a primary home often takes about six to eight months. Most of that time passes before any foreclosure notice is sent.
Texas is mainly a nonjudicial state. Most home loans use a deed of trust with a power of sale, so the lender does not need a lawsuit to sell. Once the formal notices start, the statute's minimum periods add up to only about six weeks, with the sale then landing on the next eligible first Tuesday. Real cases can take longer when servicers pause for loss mitigation or a sale is postponed.
How long does foreclosure take in Texas?
- 1
120+ days late
Federal rule before first notice.
- 2
20-day cure
Notice of default and right to cure.
- 3
21-day notice
Posted, filed and mailed.
- 4
First Tuesday
Courthouse sale.
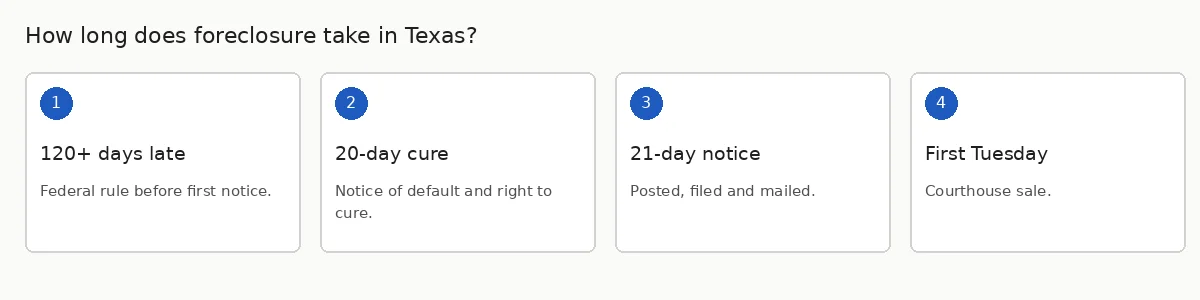
Minimum periods once the formal notices begin.
Stage 1: the 120-day federal waiting period
Before Texas notice rules even apply, federal servicing rules usually hold foreclosure back. A servicer generally cannot make the first notice or filing until the borrower is more than 120 days delinquent under 12 CFR 1024.41(f).
During those four months you will get calls, late notices and loss mitigation letters. This is the easiest time to arrange a repayment plan, forbearance or a modification, and to sell with the most flexibility. The behind on payments hub collects those options.
Stage 2: notice of default and the 20-day cure period
For a debt secured by a residence, Texas Property Code section 51.002(d) requires the servicer to send written notice that the debtor is in default and give the debtor at least 20 days to cure before notice of sale can be given.
This letter often comes with a notice of acceleration or intent to accelerate. Read it for the amount needed to cure and the deadline. If you can bring the loan current, this is the moment to do it. If you cannot, request written reinstatement and payoff figures right away. Our guide on what to do after a notice of default covers the first two weeks.
Stage 3: notice of sale at least 21 days before the auction
After the cure period ends, the lender must give notice of sale at least 21 days before the sale date. Section 51.002(b) requires the notice to be posted at the courthouse door, filed with the county clerk and sent by certified mail to each debtor.
The notice names the date, the county and the earliest time the sale will begin. Because sales happen only once a month, a notice posted just after a cutoff can push the sale to the following month. Check the county clerk's foreclosure postings to confirm the date for your property.
What day are foreclosure sales in Texas?
Under section 51.002(a), a sale must take place between 10 a.m. and 4 p.m. on the first Tuesday of a month, at the area of the county courthouse designated by the commissioners court. If January 1 or July 4 falls on that Tuesday, the statute moves the sale to the first Wednesday.
After the cure period ends, the lender must give notice of sale at least 21 days before the sale date.
County examples: where sales are posted
Each county clerk keeps the posted notices and each commissioners court designates where sales happen. Check your county's official page for the current list.
- Harris County: the Harris County Clerk publishes foreclosure notices filed for the monthly sales.
- Dallas County: the Dallas County Clerk records and posts notices of trustee sales.
- Bexar County: the Bexar County Clerk maintains the foreclosure notice records for the county.
If you live in one of these areas, our Texas sell page and the Houston and San Antonio pages explain local selling steps.
Texas home equity loans take longer
A Texas home equity loan cannot be foreclosed the same way. The Texas Constitution, article XVI, section 50(a)(6) says such a loan may be foreclosed upon only by a court order.
Lenders use an expedited court process, which adds filing, service and a hearing before the sale is authorized. That can add a few months. If you have both a first mortgage and a home equity loan, either lender may start its own process. Our home equity loan sale guide explains paying off both at closing.
Is there a right of redemption after a Texas foreclosure?
For a standard mortgage foreclosure, generally no. Once the trustee's sale is completed, the former owner has no statutory right to buy the house back.
Two exceptions are worth knowing. Owners can redeem from an HOA assessment foreclosure within 180 days after the association mails notice of the sale, under Property Code section 209.011. And property sold at a tax sale may be redeemed under Tax Code section 34.21: generally two years for a homestead and 180 days for most other property. See selling a house with an HOA lien for the association side.
How long do you have to move out after a Texas foreclosure?
After the sale, the buyer must give written notice to vacate, usually at least three days, before filing an eviction suit, under Property Code section 24.005. Tenants with a lease can have more time under federal and state rules. Plan your move before sale day instead of after.
Worked example: selling inside the timeline
Illustrative numbers only. A Fort Worth homeowner missed payments starting in March. The cure notice arrives in mid-August, and the sale is posted for the first Tuesday in October. She owes $148,000 plus $9,400 in arrears and fees. The house needs a roof and is worth about $210,000 as-is.
She signs a sale on September 3 at $199,000. After the $157,400 payoff and $5,500 in other costs, she keeps about $36,100, and the posted sale is cancelled when the loan is paid. Had she waited past the first Tuesday, that equity would have depended on the auction bid.
When a cash sale may not be your best option
A cash sale is not the right move if you can cure the default during the 20-day window, if a loan modification makes the payment affordable, or if months remain and the house is ready to list. Those paths usually keep more of your money.
Use the cash offer vs listing guide to compare written net proceeds, and review how to avoid foreclosure. A fast as-is sale fits when a first-Tuesday date is already posted or the house needs work.
Key takeaways
- Texas foreclosures are usually nonjudicial and move quickly once notices start.
- Federal rules generally require more than 120 days of delinquency first.
- Texas requires at least a 20-day cure notice and 21 days' sale notice.
- Sales happen on the first Tuesday of the month between 10 a.m. and 4 p.m.
- Home equity loans need a court order, and standard foreclosures have no redemption.
The bottom line
In Texas, the clock runs short once the cure notice arrives, so act on the first letter. Get your figures in writing, check the county posting, and compare keeping, reworking or selling. If selling fits, request a written cash offer; SilverCrest Estates can close in as little as 21 days when title and the lender payoff allow.
Frequently asked questions
How long does foreclosure take in Texas?
A standard nonjudicial foreclosure on a primary home often takes about six to eight months from the first missed payment. Once formal notices start, Texas minimums add up to about six weeks before a first-Tuesday sale.
What day are foreclosure sales in Texas?
Sales are held between 10 a.m. and 4 p.m. on the first Tuesday of the month at the area of the county courthouse designated by the commissioners court.
Can you get your house back after foreclosure in Texas?
Generally not after a standard mortgage foreclosure. Texas allows redemption after an HOA assessment foreclosure, within 180 days of the notice of sale, and after a tax sale under Tax Code section 34.21.
Sources & further reading
Primary sources we consulted for this article. Rules vary by state and change over time — always confirm against the original source.
- 1Texas Property Code chapter 51
Texas Constitution and Statutes
Section 51.002 notice periods and first-Tuesday sale timing.
- 2Texas Constitution article XVI
Texas Constitution and Statutes
Home equity loans may be foreclosed only by court order.
- 3Texas Property Code chapter 209
Texas Constitution and Statutes
180-day redemption after an HOA assessment foreclosure.
- 412 CFR 1024.41 Loss mitigation procedures
Cornell Legal Information Institute
120-day federal waiting period before first notice.
About the author
Michael Thompson
Property Specialist
Michael Thompson works with the SilverCrest Estates acquisitions team, helping homeowners across 50+ US markets understand their options and close on their own timeline.
Disclaimer: This article is for general information only and is not legal, tax, or financial advice. Real estate rules vary by state and change over time. Consult a licensed attorney, tax professional, or financial advisor about your specific situation before acting.